How Much CGL ELEKTRONIK Costs in 2026: A Price Guide
As an entrepreneur in the dynamic electronics sector, you’re focused on innovation, sales, and growth. Yet, a single unforeseen accident—a customer slipping in your store, or a product causing property damage—can threaten everything you’ve built. This is where commercial general liability insurance becomes your business’s most critical safeguard.
But a significant question looms for every business owner planning their budget: How much does commercial general liability ELEKTRONIK cost in 2026? The answer isn’t a simple number; it’s a calculated figure based on your unique business risks. Predicting these costs is essential for financial stability and strategic planning in the years ahead.
This comprehensive guide will demystify the pricing landscape for 2026. We will explore the average premiums you can expect, break down the key factors that influence your final rate, and provide actionable strategies to secure the best possible coverage without overpaying. Let’s ensure your business is protected and your budget is on point.
Understanding CGL ELEKTRONIK Cost Averages in 2026
Navigating the world of business insurance can feel overwhelming, but understanding the basics is the first step toward making an informed decision. For any electronics-focused business, a CGL policy is the foundation of your risk management strategy. It’s designed to protect your assets if you’re sued for causing property damage, bodily injury, or personal injury (like libel or slander).
Imagine a customer in your repair shop trips over a power cord and breaks their wrist, leading to medical bills and a lawsuit. Or, consider a scenario where an electronic component you sold malfunctions and causes a small fire in a client’s office. A CGL policy is designed to cover the legal fees, settlements, and medical costs associated with these types of claims.
What is Commercial General Liability ELEKTRONIK?
Commercial General Liability (CGL) for an ELEKTRONIK business is a specific type of policy that covers common business risks. It’s not about your own injuries or property damage, but rather the harm your business operations could cause to a third party—namely, customers, vendors, or other members of the public.
This coverage is crucial for businesses with a physical location, those that interact with clients face-to-face, or even e-commerce sellers whose products could potentially cause harm. It provides a vital financial safety net against the high cost of lawsuits and claims that could otherwise bankrupt a small business.
Average Annual and Monthly Premiums for Small Businesses
While every policy is unique, we can provide a reliable forecast for planning purposes. In 2026, most small to medium-sized electronics businesses can expect to pay between $500 and $1,800 per year for a standard $1 million/$2 million general liability policy. This breaks down to a more manageable monthly cost of approximately $40 to $150.
It’s important to remember this is a general range. A low-risk online consultant might be at the lower end of that spectrum, while an electronics manufacturer with heavy machinery and more public exposure will trend toward the higher end. The core question of how much does commercial general liability ELEKTRONIK cost in 2026 ultimately depends on your specific risk profile.
Why 2026 Premiums Are Expected to Shift
The insurance market is not static. Several macroeconomic factors are expected to influence premiums heading into 2026. General inflation continues to increase the cost of materials, repairs, and medical care, which directly impacts the potential size of a claim payout. Insurers adjust their rates to account for these higher potential costs.
Furthermore, an increasingly litigious environment, often referred to as “social inflation,” means that juries are awarding larger settlements in liability cases. Insurers must price this trend into their policies. Finally, global supply chain disruptions can delay repairs and increase costs, adding another layer of risk that affects overall premium calculations.
Key Factors That Determine Your ELEKTRONIK Liability Premium
Your insurance premium is not an arbitrary number. It is the result of a detailed underwriting process where an insurer assesses the specific risks your business presents. Understanding these factors empowers you to take control and potentially lower your costs. The final price tag for your coverage is a direct reflection of your operational details.
Think of it like a puzzle. The insurance company pieces together information about your industry, location, size, and history to create a complete picture of your risk. The clearer and safer that picture is, the more favorable your premium will be. For an in-depth look, you can explore the various factors affecting your Commercial General Liability ELEKTRONIK premiums in our detailed guide.
Your Business’s Specific Industry and Risk Level
The type of work you do within the electronics field is the single most significant cost driver. An e-commerce business selling pre-packaged consumer electronics has a much lower risk profile than a company that manufactures and installs custom high-voltage industrial components.
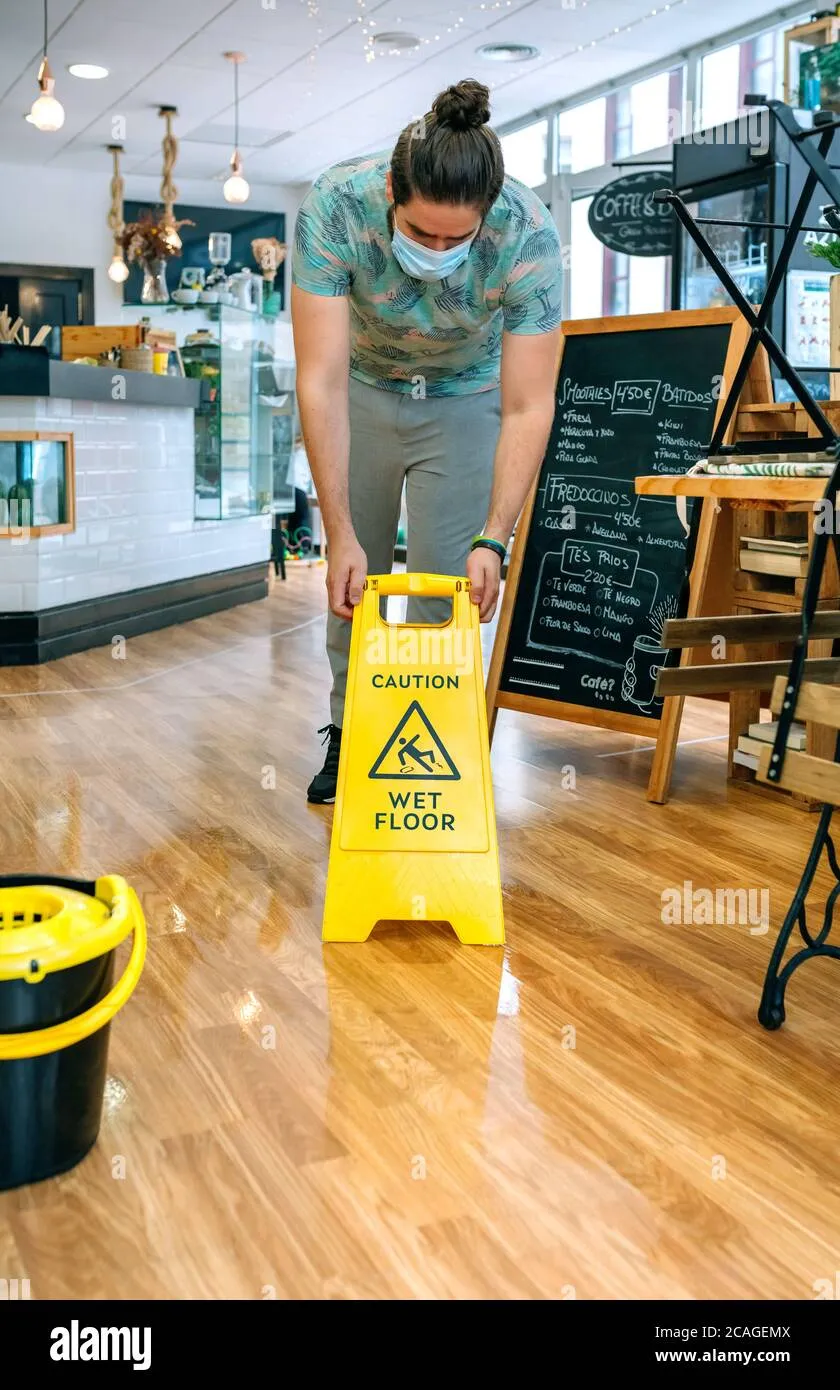
Insurers classify businesses based on perceived risk. A retail store’s primary risk is slip-and-falls (premises liability), while a repair shop’s risk includes damaging a customer’s expensive device (operations liability). A manufacturer faces the highest risk, as a product defect could lead to widespread property damage or injury (products-completed operations liability).
The Impact of Your Location and State Regulations
Where you operate matters significantly. A business located in a densely populated urban area will typically pay more than a similar business in a rural setting due to the higher volume of foot traffic and potential for accidents. Furthermore, some states have legal climates that are more favorable to plaintiffs, leading to more lawsuits and higher settlements.
States like California, New York, and Florida are known for being more litigious, and insurance premiums there often reflect this increased risk. Insurers track claim data by zip code and adjust their rates accordingly based on local history, weather risks (like hurricanes or floods affecting premises), and state laws.
Coverage Limits and Deductible Choices
Your policy’s structure also plays a major role in its cost. Coverage limits refer to the maximum amount an insurer will pay out for a covered claim. A standard policy might offer a $1 million per-occurrence limit and a $2 million aggregate limit. Opting for higher limits, such as $2 million per-occurrence, will provide more protection but also increase your premium.
Your deductible is the amount you agree to pay out-of-pocket before your insurance coverage kicks in. Choosing a higher deductible, say $2,500 instead of $500, demonstrates to the insurer that you are willing to share more of the risk. This will almost always result in a lower annual premium.
Cost Comparison by ELEKTRONIK Business Type
To truly understand how much does commercial general liability ELEKTRONIK cost in 2026, it’s helpful to see estimates broken down by business category. The day-to-day operations and associated risks vary dramatically between a retail storefront and a B2B consulting firm, and insurers price their policies to reflect these differences. The following table provides a clear comparison of what different types of electronics businesses might expect to pay.
Use this table as a benchmark to gauge where your business might fall. Keep in mind that these are estimates, and your final quote will depend on the specific factors we’ve discussed, such as your location, claims history, and chosen coverage limits.
| Business Type | Estimated Annual Premium (2026) | Common Risks Covered | Key Cost Driver |
|---|---|---|---|
| Electronics Retail Store | $500 – $1,200 | Customer slip-and-falls, falling merchandise, advertising injury. | Volume of foot traffic and physical store size. |
| Electronics Repair Shop | $600 – $1,500 | Accidental damage to customer property, data loss claims, customer injury on premises. | Value of customer equipment being handled. |
| E-commerce Electronics Seller | $450 – $900 | Product liability (if product causes harm), copyright infringement in listings, data breaches. | Type and volume of products sold; data security measures. |
| Component Manufacturer | $1,200 – $5,000+ | Widespread product failure causing property damage or injury, workplace accidents affecting visitors. | Product’s application (e.g., consumer vs. aerospace) and quality control record. |
| IT/Electronics Consultant | $400 – $750 | Property damage at a client’s site, accidental data deletion, slander/libel claims. | Extent of on-site work and nature of advice given. |
Pro Tips for Reducing Your CGL ELEKTRONIK Costs
While insurance is a necessary expense, it doesn’t have to be an uncontrollable one. There are several proactive steps you can take to manage and reduce your premiums. By demonstrating to insurers that you are a lower-risk client, you can gain access to more favorable rates. This involves a combination of smart safety practices, strategic policy choices, and savvy shopping.
Implementing these tips not only helps lower your insurance costs but also makes your business safer and more resilient overall. It’s a win-win situation that protects your bottom line and your company’s future. The process of finding the right coverage at the right price is a crucial business skill.
Implement a Robust Risk Management Program
The most effective way to lower your insurance costs is to reduce the likelihood of a claim. Develop and document a formal safety program. This should include regular employee training on safety protocols, clear procedures for keeping your premises free of hazards (like spills or clutter), and a quality control process for any products you sell or repair.
Documenting these efforts is key. When you can show an underwriter a written safety manual and training logs, it proves you are serious about risk mitigation, which can lead to significant discounts.
The Benefits of Bundling Policies
Don’t just buy a standalone general liability policy. Ask your insurance agent about a Business Owner’s Policy (BOP). A BOP conveniently bundles general liability with commercial property insurance and often other coverages like business interruption insurance, usually at a lower price than buying each policy separately.
Insurers love to bundle because it increases customer loyalty and simplifies their administrative process. They pass these savings on to you in the form of a discounted package premium, making it one of the easiest ways to save money.
Shop Around and Compare Quotes Annually
Insurance is a competitive market. Never accept the first quote you receive, and don’t automatically renew with your current provider without checking other options. The process of getting the best business ELEKTRONIK quotes is crucial for ensuring you’re not overpaying.
Rates and appetites for risk can change annually among insurers. Work with an independent agent who can source quotes from multiple carriers to find the best combination of coverage and price for your specific needs. This simple step can save you hundreds of dollars each year.
Maintain a Good Claims History
Your claims history is like a credit score for your business insurance. A history free of claims, or with only minor incidents, demonstrates that your risk management is effective. Insurers reward this with lower premiums and “claims-free” discounts over time.
For very small incidents, consider whether it’s more cost-effective to pay out-of-pocket rather than file a claim that could raise your rates for years to come. Always weigh the short-term cost against the long-term impact on your insurance premiums.
Frequently Asked Questions about How Much Does Commercial General Liability ELEKTRONIK Cost in 2026?
Here are answers to some of the most common questions business owners have about the cost of CGL insurance.
What is the absolute cheapest CGL policy I can get?
The cheapest policies are typically for low-risk, home-based businesses like solo consultants, with minimal coverage limits and high deductibles. While a low price is tempting, it’s crucial to ensure the policy provides adequate protection for your specific risks.
Does my home-based electronics business need CGL?
Yes, most likely. Your homeowner’s insurance policy almost certainly excludes business-related liability. If a client visits your home and gets injured, or a product you ship causes damage, you would need a CGL policy to be covered.
How often will my premium change?
Your premium is typically set for a one-year term. It will be re-evaluated at renewal and can change based on factors like your claims history, changes in your business operations (like opening a new location), or general rate adjustments by the insurer.
What’s the difference between CGL and Professional Liability?
CGL covers physical risks like bodily injury and property damage. Professional Liability (also called Errors & Omissions) covers financial losses to a client caused by your professional mistakes, such as giving faulty advice or making a critical error during a service.
Can I pay my CGL premium monthly?
Yes, nearly all insurance carriers offer monthly payment plans. While there might be a small administrative fee for this convenience, it can greatly help with cash flow management for a small business.
Does CGL cover product recalls for my electronic devices?
No, standard CGL policies explicitly exclude the costs associated with a product recall. This would require a separate, specialized Product Recall Insurance policy, which is crucial for manufacturers.
What happens if I let my CGL coverage lapse?
Letting your coverage lapse leaves your business completely exposed to lawsuits, which could be financially devastating. It can also make it more difficult and expensive to get coverage in the future, as insurers view a coverage gap as a sign of higher risk.
How can I find the best CGL provider?
Finding the right provider involves more than just price. You should look for insurers with strong financial ratings and good customer service reviews. Our guide on the Top 10 Best Commercial General Liability ELEKTRONIK for Small Businesses in 2026 is an excellent resource for comparing top-rated carriers.
Securing Your Business’s Future
Ultimately, budgeting for your policy starts with understanding the core question: how much does commercial general liability ELEKTRONIK cost in 2026? As we’ve seen, the cost is not a fixed price but a dynamic figure influenced by your industry, location, coverage choices, and commitment to safety. By anticipating an annual premium between $500 and $1,800, you can create a realistic budget that treats this crucial protection as a planned investment rather than an unexpected burden.
Don’t view insurance as just an expense; see it as an essential tool that enables growth and provides peace of mind. By taking proactive steps to manage your risk and actively shopping for the best policy, you can secure robust protection that fits your budget. Now is the time to assess your needs, implement safety protocols, and connect with a qualified agent to ensure your electronics business is financially protected for whatever comes next.
Originally posted 2026-05-04 15:35:23.