Choosing CGL ELEKTRONIK Limits for Your Small Business
As a small business owner, you juggle countless responsibilities, from product development to customer service. Amidst this daily hustle, it’s easy to overlook the finer details of your business insurance. Yet, one of the most critical decisions you’ll make is choosing the right CGL ELEKTRONIK limits and deductibles for your small business, a choice that could one day mean the difference between financial stability and devastating loss.
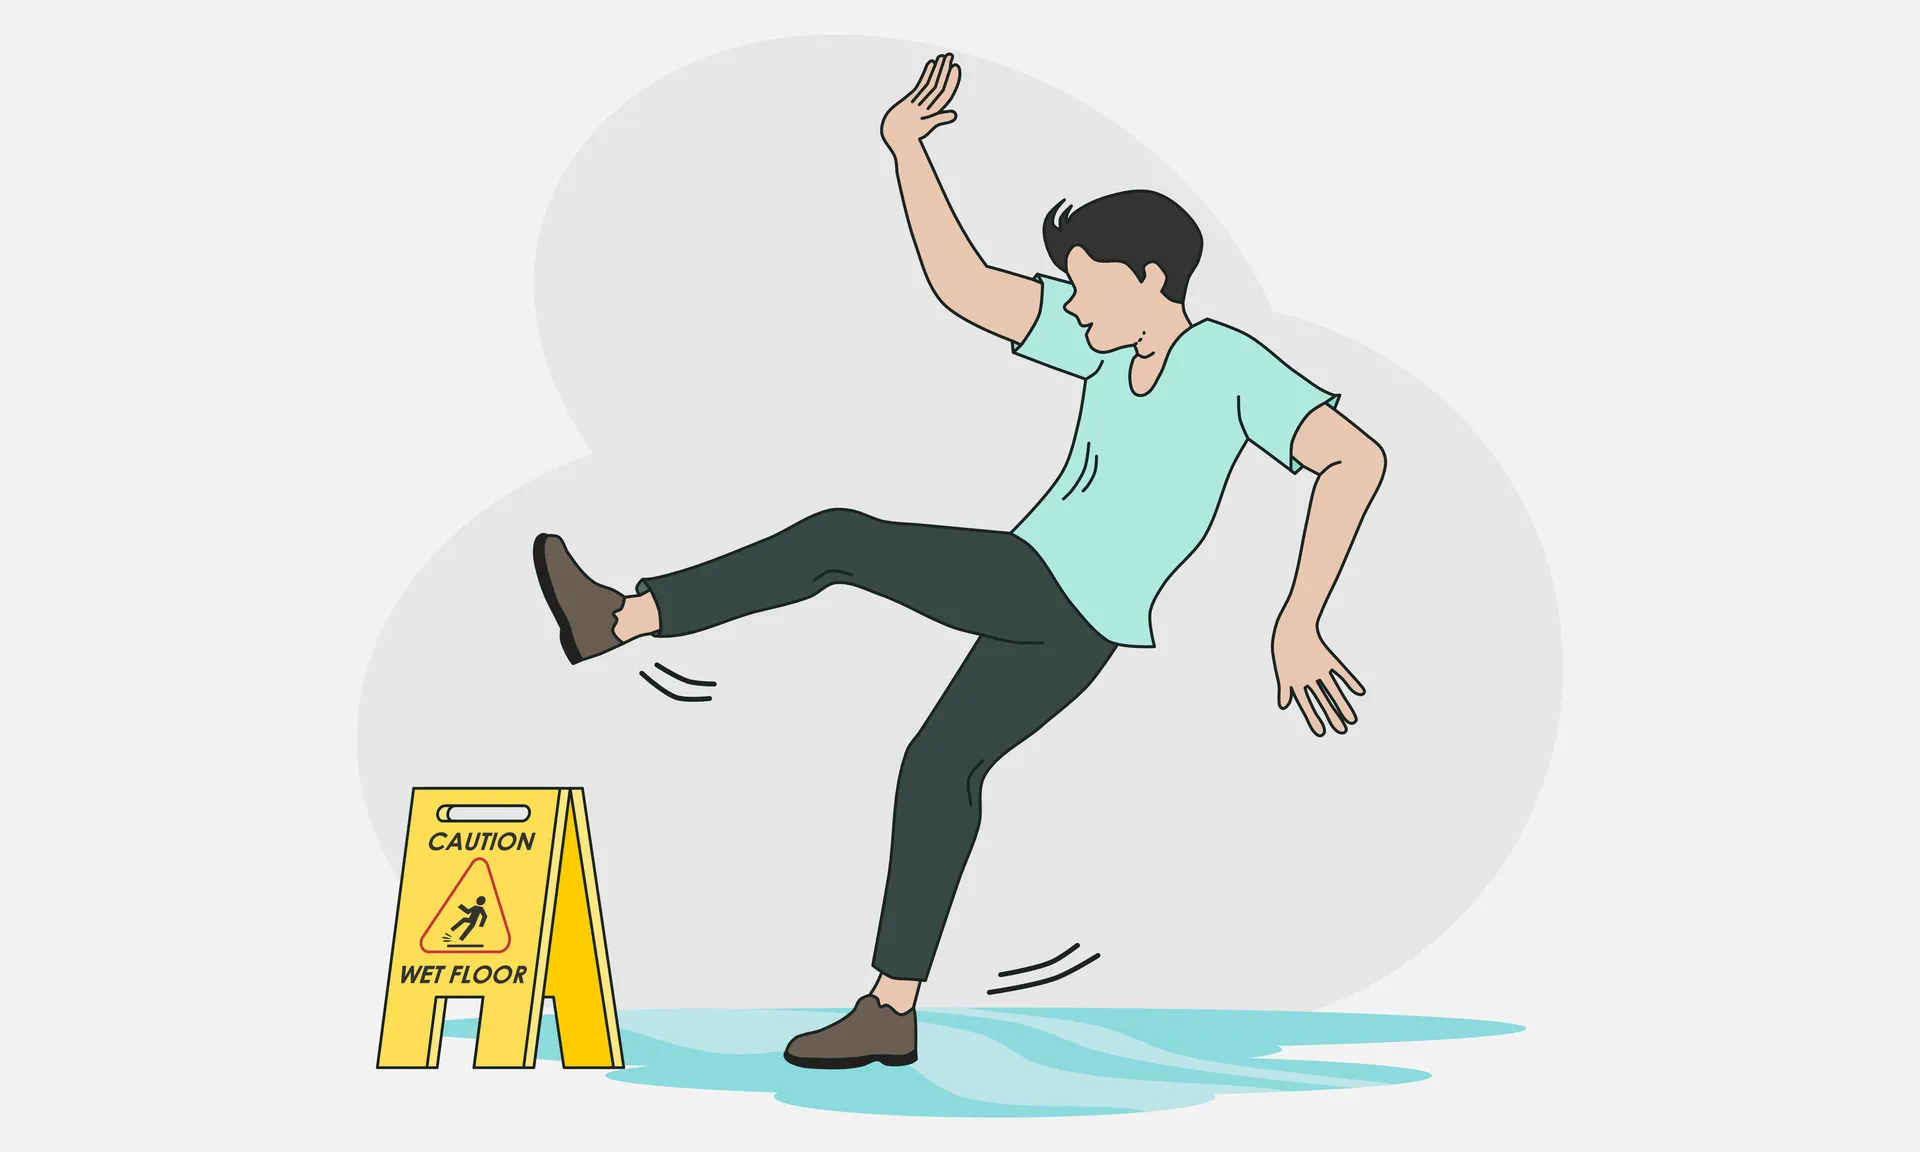
Imagine a customer slipping on a wet floor in your shop, a faulty product causing damage, or an advertising campaign unintentionally infringing on a copyright. These are not just hypotheticals; they are real-world risks that Commercial General Liability (CGL) insurance is designed to cover. But having a policy isn’t enough. The specific limits and deductibles you select determine the strength of your financial safety net.
This comprehensive guide will demystify the process. We will break down what coverage limits and deductibles are, how to assess your unique business risks, and how to strike the perfect balance between robust protection and an affordable premium. By the end, you’ll have the confidence to make an informed decision that safeguards your hard-earned success.
What Are CGL ELEKTRONIK Limits and Deductibles?
Before you can select the right coverage, you must understand the fundamental building blocks of any CGL ELEKTRONIK policy: the limits and the deductible. These two figures work in tandem to define how your insurance responds when a claim is filed against your business.
Think of them as the rules of engagement for your financial protection. Getting them wrong can leave you dangerously underinsured or paying for coverage you don’t need. Let’s break down each component so you can navigate your policy with clarity.
Decoding Your Coverage Limits
A coverage limit is the absolute maximum amount of money your insurance provider will pay out for a covered claim. If a lawsuit results in a $1.2 million judgment against your business but your policy limit is $1 million, you are personally responsible for the remaining $200,000.
CGL policies typically feature two primary types of limits, which we’ll explore in more detail later: a “per-occurrence” limit for a single incident and a “general aggregate” limit for the total of all incidents within your policy term.
The Role of the Deductible
The deductible is the amount of money you must pay out of pocket for a claim before your insurance coverage begins to pay. For example, if you have a $5,000 deductible and face a covered claim of $50,000, you pay the first $5,000, and your insurer covers the remaining $45,000.
A deductible helps prevent small, minor claims from being filed, which keeps the insurance system more efficient. It also means you share a small portion of the risk with the insurer, which can influence your premium costs.
The Inverse Relationship Between Premiums and Deductibles
One of the key financial levers you can pull is the relationship between your deductible and your premium. Generally, a higher deductible signals to the insurer that you are willing to take on more initial risk yourself. In return, they typically offer you a lower monthly or annual premium.
Conversely, a lower deductible means the insurer will have to pay out sooner and on smaller claims, so they charge a higher premium to compensate for that increased risk. Understanding the many factors affecting your Commercial General Liability ELEKTRONIK premiums is essential to finding this balance.
Understanding Aggregate vs. Per-Occurrence Limits
When you look at a CGL ELEKTRONIK insurance quote, you’ll almost always see two numbers presented together, such as “$1,000,000 / $2,000,000.” This isn’t just random industry jargon; it represents the two most important limits in your policy: the per-occurrence limit and the general aggregate limit. Understanding the distinction is vital for ensuring you have adequate protection throughout your entire policy year.
Failing to grasp this difference can lead to a false sense of security. You might think you’re fully covered, only to discover your protection has been exhausted after a series of unfortunate events.
Defining the Per-Occurrence Limit
The per-occurrence limit is the maximum amount your insurer will pay for any single claim or incident. The first number in the “$1M/$2M” example is the per-occurrence limit. This means for a single lawsuit, whether it’s for bodily injury, property damage, or another covered event, the most your policy will pay out is $1 million.
This limit protects your business from a single, catastrophic event. If a customer has a severe slip-and-fall accident in your store and wins a judgment of $750,000, your policy would cover the full amount (less your deductible), as it falls below the $1 million per-occurrence limit.
Defining the General Aggregate Limit
The general aggregate limit is the absolute total amount your insurer will pay out for all claims combined during your policy period, which is typically one year. This is the second number in the “$1M/$2M” example. No matter how many individual claims you have, the total payout for the year cannot exceed this $2 million cap.
Think of it as the total amount of insurance money in your “bank” for the year. Each claim payment, whether it’s $50,000 or $500,000, gets deducted from this aggregate limit. Once it’s gone, your coverage for the year is exhausted unless you have additional policies.
Why Both Limits Matter for Comprehensive Protection
Both limits are critically important. A high per-occurrence limit protects you from a single large disaster. However, a business could face multiple smaller claims in a single year—for instance, three separate incidents resulting in claims of $400,000, $500,000, and $600,000.
Each of these claims falls under the $1 million per-occurrence limit. But combined, they total $1.5 million, which is well within the $2 million general aggregate limit. If your aggregate limit was only $1 million, you would be personally responsible for the final $500,000, even though no single claim exceeded the per-occurrence cap.
How to Assess Your Small Business’s Liability Risk
The process of choosing the right CGL ELEKTRONIK limits and deductibles for your small business is not a guessing game. It requires a thoughtful and honest assessment of your specific risk exposure. A freelance graphic designer working from home has a vastly different risk profile than a general contractor managing a busy construction site. Tailoring your coverage to your risk is key to getting value from your policy.
By analyzing a few key areas of your operations, you can develop a clear picture of your potential liability and select limits that provide a genuine safety net.
Analyzing Your Industry and Services
Your industry is the number one factor in determining risk. Businesses with high levels of public interaction, that perform work on client property, or that produce physical products generally carry higher risk.
- High-Risk Industries: Construction, restaurants, bars, manufacturing, and childcare facilities. These businesses have a high potential for bodily injury or property damage claims.
- Moderate-Risk Industries: Retail stores, consulting firms with office-based client meetings, and auto repair shops.
- Low-Risk Industries: Home-based freelancers, online-only businesses, and consultants who work remotely.
The higher your industry’s inherent risk, the higher your CGL limits should be. A standard $1M/$2M policy is often just the starting point for high-risk operations.
Considering Your Physical Location and Foot Traffic
Where you conduct business matters immensely. A bustling retail store in a high-traffic mall has a much greater chance of a slip-and-fall incident than a by-appointment-only office on the 10th floor of a secure building.
Consider how many non-employees enter your premises each day. The more people who walk through your doors, the greater your exposure to “premises liability” claims. This factor directly influences the per-occurrence limit you should consider.
Evaluating Contractual Requirements
Often, the decision is made for you. Many commercial leases, client contracts, and vendor agreements will explicitly state the minimum CGL insurance limits you must carry to do business with them. This is non-negotiable.
Before signing any contract, review the insurance requirements section carefully. It will typically specify both a per-occurrence and an aggregate limit. Failing to meet these requirements can put you in breach of contract and leave you uninsured for work performed for that client. Always ensure your policy meets or exceeds these third-party mandates.
A Comparative Look at CGL ELEKTRONIK Policy Structures
To provide a clearer picture, let’s compare how different types of small businesses might approach their CGL ELEKTRONIK policy structure. The table below illustrates typical limits and deductibles based on varying risk profiles. This is a general guide; your specific needs should always be discussed with an insurance professional.
| Feature | Low-Risk Business (e.g., Solo Consultant) | Moderate-Risk Business (e.g., Retail Shop) | High-Risk Business (e.g., General Contractor) |
|---|---|---|---|
| Typical Per-Occurrence Limit | $500,000 to $1,000,000 | $1,000,000 (Industry Standard) | $1,000,000 to $2,000,000+ |
| Typical Aggregate Limit | $1,000,000 to $2,000,000 | $2,000,000 (Industry Standard) | $2,000,000 to $5,000,000+ |
| Recommended Deductible Range | $1,000 – $2,500 | $1,000 – $5,000 | $2,500 – $10,000+ |
| Key Considerations | Mainly driven by client contract requirements. Low premises risk. | High premises liability due to foot traffic. Potential product liability. | High risk of property damage and bodily injury. Often requires an Umbrella Policy. Strict contractual minimums are common. |
Expert Tips for Optimizing Your CGL ELEKTRONIK Policy
Navigating the world of commercial insurance can feel complex, but a few strategic principles can guide you. Optimizing your policy is about more than just finding the cheapest price; it’s about securing the best possible value and ensuring your coverage truly meets your needs. A thoughtful strategy is a core part of choosing the right CGL ELEKTRONIK limits and deductibles for your small business.
- Start with the Industry Standard: For most small businesses, a policy with limits of $1 million per-occurrence and $2 million in aggregate is the accepted industry standard. This is a solid baseline to start from and will satisfy the requirements of most commercial leases and client contracts.
- Don’t Choose a Deductible You Can’t Afford: While a high deductible of $10,000 might significantly lower your premium, ask yourself if you could comfortably write a check for that amount tomorrow if a claim occurred. Your deductible should be an amount you can pay without causing severe cash flow problems for your business.
- Review Your Policy Annually: Your business is not static, and neither are its risks. Review your coverage every year before renewal. Have you hired more employees, moved to a larger location, or started offering new, riskier services? Your limits may need to adjust to match your growth.
- Consider an Umbrella Policy for Extra Protection: If your risk assessment suggests you need more than a standard CGL policy can offer, a commercial umbrella policy is an affordable way to add an extra layer of liability protection (often in increments of $1 million) on top of your existing limits.
- Work with an Experienced Insurance Broker: A knowledgeable broker who specializes in your industry can be an invaluable asset. They understand the unique risks you face and can help you compare options from multiple carriers to find the best fit. A great place to start is by reviewing a list of the Top 10 Best Commercial General Liability ELEKTRONIK for Small Businesses in 2026.
- Document Your Safety Protocols: Insurers look favorably on businesses that are proactive about risk management. Having documented safety procedures, employee training programs, and regular maintenance schedules can sometimes lead to better premium rates. When vetting potential insurers, it’s wise to consider what to look for in a Commercial General Liability ELEKTRONIK provider beyond price, such as their approach to risk management.
Frequently Asked Questions about Choosing the Right CGL ELEKTRONIK Limits and Deductibles for Your Small Business
What is a typical CGL limit for a small business?
The most common starting point for small businesses is a $1 million per-occurrence limit and a $2 million general aggregate limit. This is often sufficient for low-to-moderate risk operations and satisfies most standard contractual requirements.
Can I change my limits and deductibles mid-policy?
Yes, you can typically request to change your limits or deductibles at any time. Your insurer will “endorse” the policy with the changes, and your premium will be adjusted accordingly for the remainder of the policy term.
Does my CGL ELEKTRONIK policy cover my employees?
CGL insurance covers injuries to third parties (like customers) caused by your employees’ actions. However, it does not cover injuries sustained by your employees themselves; that is what Workers’ Compensation insurance is for.
Is a higher deductible always better for saving money?
While a higher deductible lowers your premium, it’s not always better. You must be able to comfortably afford to pay that deductible out of pocket if a claim arises. A deductible you can’t pay makes your insurance effectively useless.
What happens if a claim exceeds my policy limit?
If a judgment against your business exceeds your policy limit, your business is responsible for paying the difference. This can put your business assets, and in some cases even your personal assets, at risk to satisfy the judgment.
How do I know if my client’s insurance requirements are reasonable?
Most client requirements for $1M/$2M limits are standard and reasonable in the business world. If a client requests unusually high limits (e.g., $5M or more), it’s worth discussing with your insurance broker to see if it’s justified by the scope of work.
Does a CGL ELEKTRONIK policy cover professional mistakes?
No, CGL does not cover financial losses caused by professional errors, negligence, or failure to perform your services. For that, you need a separate policy called Errors & Omissions (E&O) or Professional Liability insurance.
What is the difference between general aggregate and products-completed operations aggregate?
The general aggregate limit applies to claims arising from your ongoing operations and premises. The products-completed operations aggregate is a separate limit that applies specifically to claims arising from your products or completed work after they have left your control.
Do I need CGL ELEKTRONIK insurance if I’m a home-based business?
Yes, in most cases. A homeowner’s policy typically excludes business-related liability. If you meet clients at home, ship products, or engage in advertising, you still have liability risks that require a CGL policy for proper protection.
The final step in choosing the right CGL ELEKTRONIK limits and deductibles for your small business involves a proactive conversation with a trusted insurance professional. Armed with the knowledge from this guide, you can ask the right questions and ensure you secure a policy that truly protects your vision. Don’t leave your business’s future to chance; make an informed choice that allows you to operate with confidence and peace of mind.
Originally posted 2026-05-01 12:07:58.